Newsletter Subscribe
Enter your email address below and subscribe to our newsletter

 ByJohn A
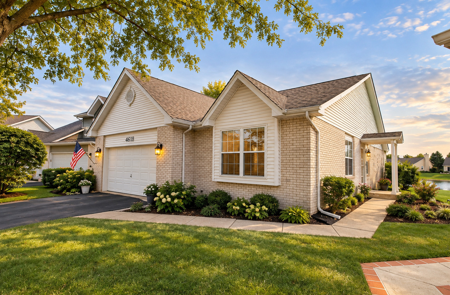
Finding a home that fits your budget involves more than looking at the asking price. Buyers must also consider property conditions, financing options, ongoing ownership expenses, and location before deciding which property offers the best value. Joliet, Illinois, is worth exploring if you are comparing housing options in the greater Chicago region and want to make an informed homebuying decision.
Searching for affordable homes Joliet IL can help you begin exploring properties that align with your preferred price range, size, and lifestyle requirements. However, affordability depends on your complete financial situation and the costs associated with maintaining a home after purchase.
By understanding the local housing market, comparing different property types, and preparing a realistic budget, you can narrow your search and focus on properties that meet your needs without creating unnecessary financial pressure.
Joliet is located in Will and Kendall counties in northeastern Illinois and forms part of the greater Chicago region. Its housing market includes a range of residential property types, giving buyers different options to evaluate based on their budget and preferences.
Before beginning your search, consider how local housing conditions, transportation, and access to everyday amenities influence the overall value of a property.
Home prices in Joliet vary according to location, property size, age, condition, and demand. Updated properties may have different asking prices from homes that require repairs or improvements. Similarly, homes with larger lots or additional living space may fall into different price categories.
Review current listings and recent comparable sales to understand the options available within your budget. Since prices and inventory change over time, use current market information rather than relying exclusively on historical averages.
Comparing Joliet with other communities around Chicago can help you determine where your budget may offer the greatest value. However, purchase price should not be the only consideration when evaluating different locations.
Include property taxes, homeowners insurance, transportation expenses, and expected maintenance costs in your comparison. A property with a lower asking price may not necessarily have the lowest overall ownership cost.
Location can influence both your daily routine and your long-term housing expenses. Consider access to employment centers, public transportation, major roads, healthcare facilities, grocery stores, and other essential amenities.
If commuting is part of your routine, estimate travel times and transportation costs before choosing a location. Reviewing these factors alongside the property’s price can help you identify a home that fits your practical needs as well as your financial goals.
The right property type depends on your household size, preferred living arrangements, maintenance expectations, and available budget. Comparing different types of homes can help you identify options that meet your requirements without paying for features you do not need.
Single-family homes offer independent living space and may include private yards, garages, and additional storage. These features can be useful for households that value privacy and outdoor space.
However, owners are generally responsible for maintaining the property, including its exterior and yard. When comparing homes, consider whether the additional space justifies the purchase price and ongoing maintenance obligations.
Condos and townhouses may offer alternatives to detached homes. Condominiums can involve shared building maintenance, while townhouse ownership arrangements vary according to the property and applicable association rules.
Before purchasing either option, review association fees, maintenance responsibilities, financial reserves where available, and restrictions affecting property use. These expenses can influence affordability even when the initial purchase price appears attractive.
Older homes may offer established layouts, mature landscaping, or architectural features that appeal to certain buyers. However, the condition of major systems and the potential need for renovations should be considered carefully.
Newer homes may include modern layouts and updated components, although they can carry higher purchase prices depending on the location and features. Compare inspection findings, expected maintenance, energy costs, and included amenities before deciding which property represents better value.
A realistic budget should account for the complete cost of purchasing and owning a home. Establishing your financial limits before viewing properties helps you avoid spending time on homes that are not financially suitable.
Start by reviewing your household income, savings, existing debt, and recurring expenses. Consider how much you can contribute toward a down payment without using funds needed for emergencies or other essential goals.
Mortgage preapproval can help you understand the loan amount a lender may be willing to offer. However, the maximum approved amount is not necessarily the amount you should borrow. Choose a purchase price that leaves sufficient room in your monthly budget for other expenses.
Mortgage principal and interest are only part of the cost of homeownership. Property taxes, homeowners insurance, electricity, heating, water, and other utilities can add significantly to your monthly expenses.
Review property-specific tax information and obtain insurance estimates before making a decision. Remember that taxes, premiums, and utility costs may change over time, so your budget should allow for reasonable increases.
Closing costs may include lender fees, appraisal charges, title-related expenses, prepaid taxes, and other transaction costs. Request a detailed estimate from your lender and relevant professionals so you understand the funds required at closing.
You should also budget for inspections, moving expenses, routine maintenance, and unexpected repairs. Maintaining an emergency reserve after purchasing the property can help you manage unplanned expenses without relying immediately on additional borrowing.
An organised property search can help you identify suitable homes more efficiently. Start with your essential requirements and use reliable listing information to compare available options.
Set a maximum purchase price and filter properties by bedrooms, bathrooms, property type, and other important features. Distinguish between essential requirements and optional preferences so that your search remains flexible.
The IvyGro platform provides property search tools designed to help users explore listings and discover homes that match their preferences. Review the available listing information carefully and confirm a property’s current status before arranging a viewing.
The asking price represents the seller’s listed price, not necessarily the amount the property will ultimately sell for. Comparing similar properties can help you assess whether a home appears reasonably priced for its characteristics and location.
Look at recent sales involving properties with comparable sizes, conditions, and features. Consider differences that could affect value, including renovations, lot size, and the condition of major systems. This information can support more informed purchasing and negotiation decisions.
Housing inventory changes as properties enter the market, receive offers, or become unavailable. Monitoring new listings can help you identify suitable options before your search becomes outdated.
Where available, set up property alerts for your preferred price range and location. Review price reductions carefully, but investigate why a property has remained on the market or changed its asking price before assuming it offers exceptional value.
A lower purchase price can be appealing, but the property’s condition and suitability deserve equal attention. Due diligence helps you understand potential expenses and determine whether the home is a sensible purchase.
Pay attention to the condition of the roof, foundation, plumbing, electrical systems, windows, and heating and cooling equipment. Problems with these components can result in significant repair or replacement expenses.
A qualified home inspector can assess visible conditions and identify concerns that may require further investigation. Consider specialist inspections when appropriate, particularly if the property shows signs of water damage, structural movement, or outdated systems.
Review the seller’s property disclosures and ask questions about known defects, previous repairs, and relevant maintenance records. Disclosures and their requirements depend on applicable laws and the circumstances of the transaction.
Use inspection findings to estimate potential repair costs before finalising your decision. Depending on the purchase agreement, inspection results may also inform negotiations or other contractual decisions. Seek appropriate professional advice when significant issues arise.
Evaluate the location according to your own priorities. Consider transportation access, nearby services, local amenities, and the distance to places you regularly visit.
Research relevant public information and property-specific restrictions where necessary. Looking beyond the asking price helps you assess whether the home will remain suitable as your needs change.
Buyers can explore several options to manage upfront expenses and make financing more manageable. The most appropriate approach depends on eligibility, loan terms, available programs, and the costs associated with the selected property.
Eligible buyers may qualify for down payment assistance, grants, or mortgage programs offered through state or local housing agencies. Requirements can vary according to income, purchase price, location, credit profile, and first-time buyer status.
Check official program information to confirm eligibility, funding availability, application requirements, and any repayment obligations. Do not assume assistance will be available until your eligibility and the program’s current terms have been verified.
Mortgage preapproval can help you establish a realistic price range and demonstrate that you have begun the financing process. Compare interest rates, loan terms, down payment requirements, and applicable mortgage insurance costs across suitable options.
Ask lenders to explain the estimated monthly payment and the funds required at closing. Understanding these figures before making an offer can help you avoid committing to a property that stretches your finances.
Real estate agent compensation is negotiable and depends on the written agreement and transaction arrangements. Buyers should understand which services are included, how compensation is determined, and who is responsible for payment.
Some eligible buyers may have access to commission rebate arrangements, subject to applicable requirements and restrictions. Review the terms carefully and confirm whether lender approval or other conditions affect how a rebate can be applied. Compare the total cost and level of representation before selecting an arrangement.
Set a maximum purchase price, review current listings, and compare properties with similar features and conditions. Include taxes, insurance, maintenance, and closing costs when deciding which homes are financially suitable.
Homeowners should budget for property taxes, insurance, utilities, maintenance, repairs, and any applicable association fees. Moving expenses and unexpected repairs can also affect your finances during the first year of ownership.
The answer depends on purchase price, location, association fees, maintenance responsibilities, and the property’s condition. Compare total ownership costs rather than assuming one property type will always be less expensive.
Some first-time buyers may qualify for assistance through eligible housing programs. Requirements vary, so check current program terms and speak with a participating lender or housing agency before relying on financial assistance.
Yes, a professional inspection can help you understand the property’s visible condition and identify potential repair concerns. Review the findings carefully and seek specialist evaluations when necessary before proceeding with the purchase.
Buying an affordable home in Joliet requires careful planning, reliable listing information, and a clear understanding of your financial limits. Comparing property types, evaluating maintenance requirements, and accounting for recurring expenses can help you make a more informed decision.
Rather than choosing a property based solely on its asking price, focus on the balance between affordability, condition, location, and long-term suitability. Use current listings to narrow your options, research available financing programs, and seek professional advice when you need help understanding a property’s value or purchase terms.
To explore available properties, review the search tools and listing information offered through the platform. If you have questions about getting started or need further assistance, visit the contact page for more information.